How to Start an Accountancy or Bookkeeping Business in the UK
Templates and forms for UK accountant / bookkeeper: Accountant / Bookkeeper business templates →
TL;DR: To start an accountancy or bookkeeping business in the UK, define your scope before choosing software, get AML supervision and practice status clear, understand that HMRC agent access is not client authority, build a careful onboarding workflow, and price around risk, volume and client behaviour.
Quick Answers For People Starting This Business
These are the questions people usually search before they commit to starting an accountancy or bookkeeping business in the UK.
How much does it cost to start an accountancy or bookkeeping business?
There is no single fixed startup cost for an accountancy or bookkeeping business. The practical budget depends on your setup, location, equipment choices and how much you can do yourself before paying for help. Common cost lines include:
- equipment and supplies
- insurance
- website or booking setup
- marketing
- software or admin tools
Start with a conservative first-month budget and a simple break-even target. That gives you a clearer answer than copying a competitor's price list.
Do you need a licence to start an accountancy or bookkeeping business?
There is not one single UK answer for every accountant or bookkeeper. Check your local council, insurer, landlord or professional body if your work involves premises, treatments, food, children, animals, regulated trades or higher-risk services.
The safest setup is to check the rules that apply to your work, then build a simple admin system before taking on too much demand.
What documents do you need to start an accountancy or bookkeeping business?
Most new businesses need a small set of working documents rather than a huge admin folder. Useful starting documents usually include:
- service terms
- client intake records
- quote or booking forms
- invoice and expense records
- cancellation or refund wording
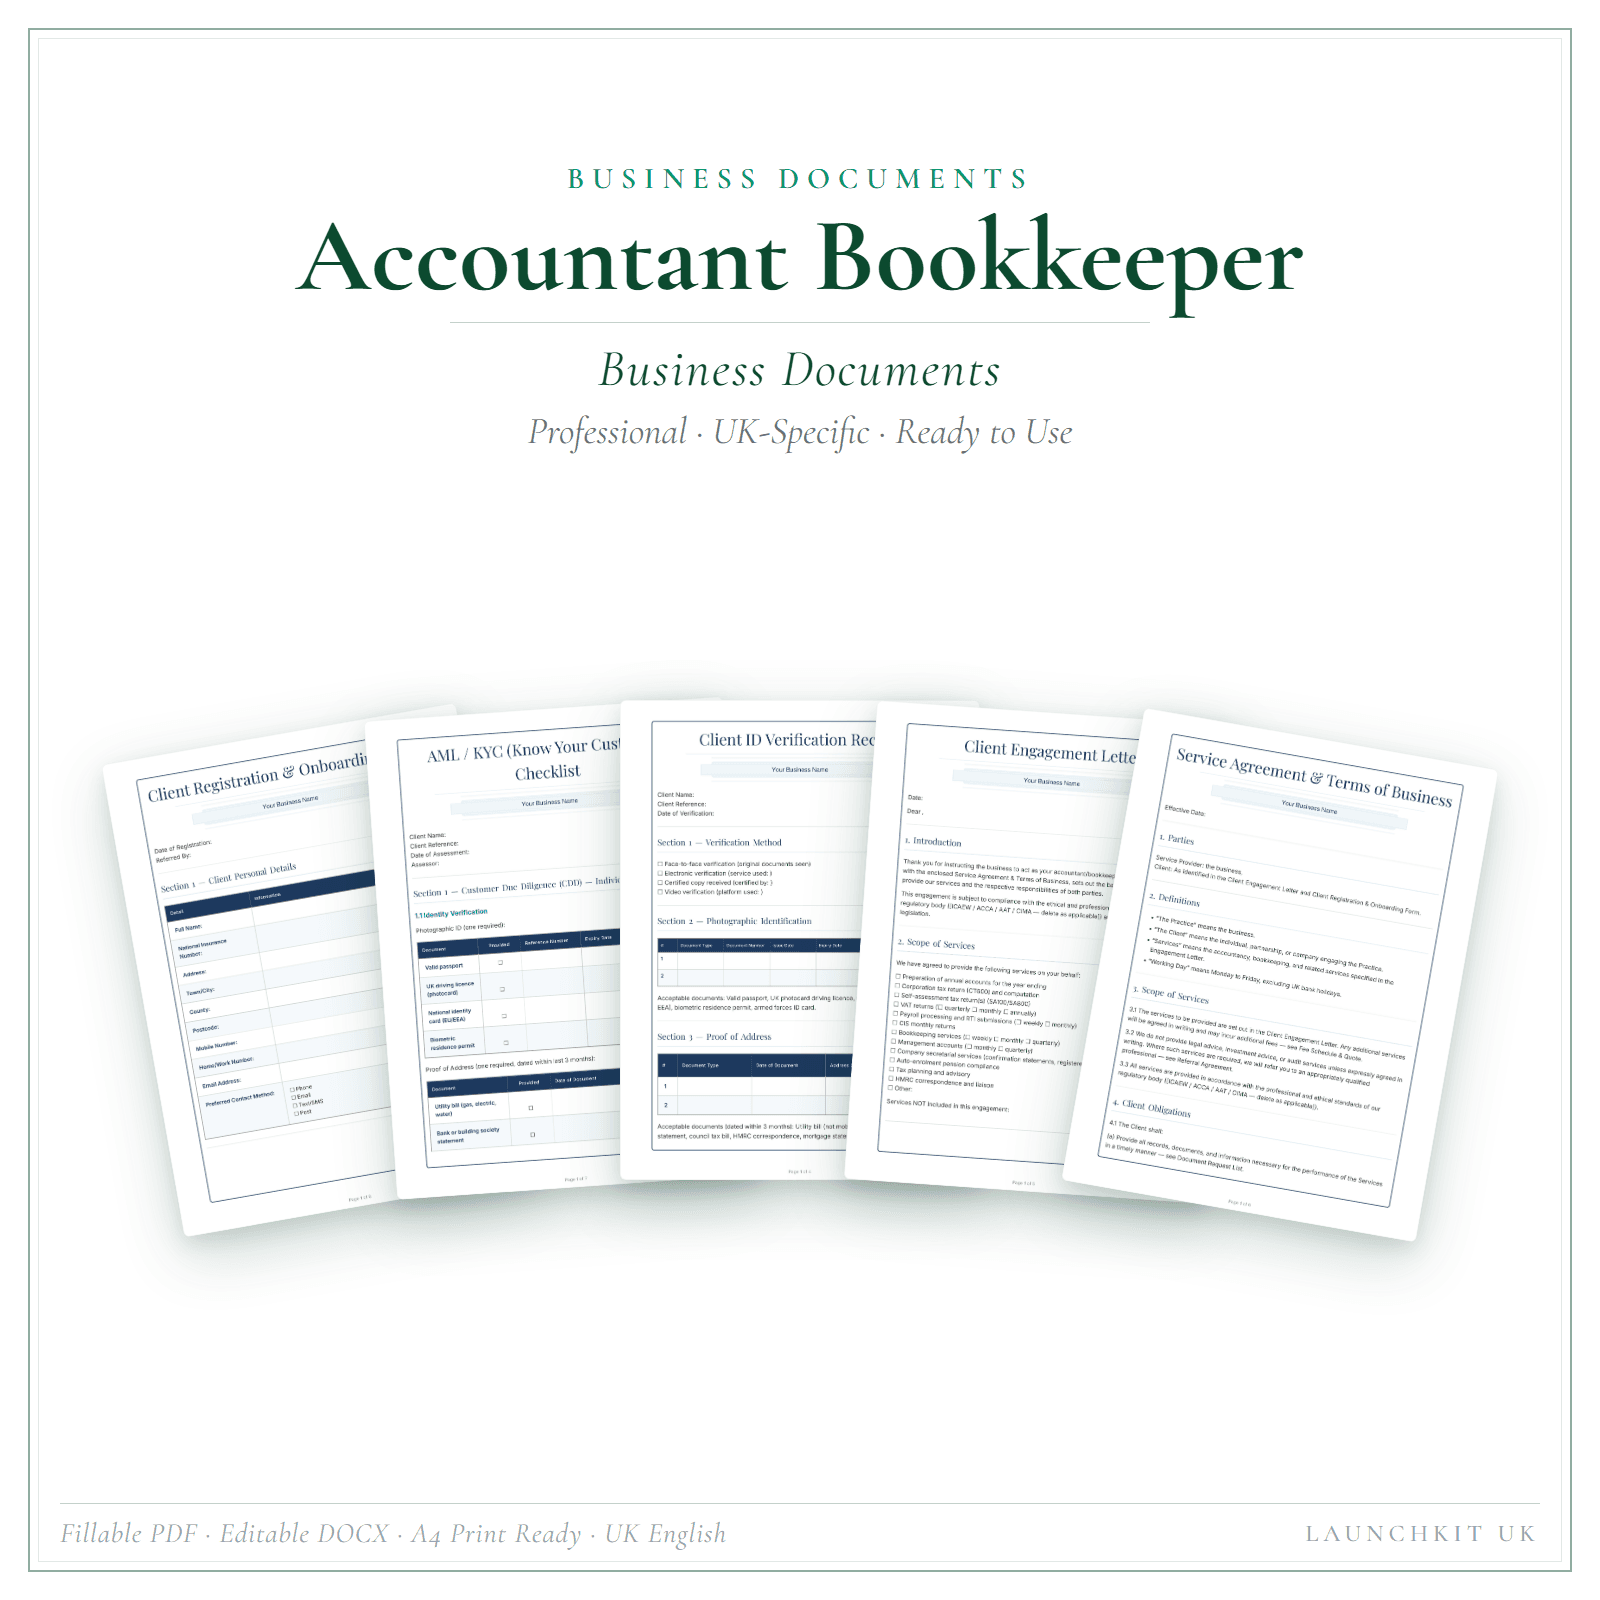
LaunchKit's Accountant / Bookkeeper business templates are designed to give you a structured starting point for that admin layer. They still need to be checked against your own business model, insurer requirements and local rules.
What should you do in the first 30 days?
In the first month, focus on evidence and repeatable habits: confirm the rules that apply to your setup, choose your service list, price from real costs, prepare client-facing terms, set up record keeping, and test your first enquiry-to-payment workflow before scaling marketing.
Starting a bookkeeping or accountancy practice is not just a matter of choosing software and finding a few clients. You are asking people to trust you with tax records, payroll details, bank transactions, Companies House deadlines and decisions that affect cash flow. That trust is valuable. It also creates duties.
The practical question is not "can I do bookkeeping?" It is "what services can I offer, under what supervision, with what evidence, and with what boundaries?" A careful answer makes the business easier to sell because clients can understand what you do and where your responsibility starts and ends.
This guide is for UK practitioners building a small bookkeeping or accountancy practice: sole practitioners, accounting technicians, finance managers moving into client work, bookkeepers leaving employment, and qualified accountants setting up a small firm. It is deliberately grounded.
Start With Scope, Not Software
The tempting first move is to pick a cloud accounting package and build the business around it. Software matters, but it should not define the practice. Scope should.
Your scope is the plain-English list of what you will and will not do for clients. It protects you from taking work outside your competence, and it protects clients from assuming that "my bookkeeper sorts everything" means you are taking full responsibility for every tax, company and employment matter in the background.
A bookkeeping practice might offer sales invoice posting, purchase invoice posting, bank reconciliations, receipt capture, VAT record preparation, payroll processing support, aged debtor reports, cash flow snapshots, and monthly management reports. An accountancy practice might add year-end accounts, corporation tax support, Self Assessment support, business structure advice, management accounts, director payroll planning, and Companies House filing support.
Some work sits outside an ordinary bookkeeping or accountancy offer. If a client asks about audit, insolvency or investment advice, check with your professional body what authorisation that work involves before you say yes, and keep it out of your service list until you have. If a client asks whether they should buy a pension, close a company, sell shares, restructure debt or claim a specialist relief, the answer may be "we can introduce you to the right adviser" rather than "yes, we can sort that".
That boundary is not weakness. It is a sign that the practice knows what it is.
Before writing a website, create a service menu with three layers:
- Core services you can deliver repeatedly and confidently.
- Add-on services you can deliver with extra checks, extra information or partner support.
- Excluded services that require a separate specialist, professional body permission, or authorisation.
Do this before taking enquiries. Once a client is worried about a deadline, scope gets emotional. A pre-written menu gives you something steady to refer back to.
Bookkeeping vs Accountancy: Draw The Line Early
Clients use the words "bookkeeper" and "accountant" loosely. Some want a tidy ledger. Some want tax planning. Some want a person who will tell them what is happening in the business before the bank balance gives them a shock.
You do not need to lecture clients on terminology, but you do need to understand the difference yourself.
Bookkeeping scope
Bookkeeping is the record-keeping engine. It turns trading activity into usable financial records.
Typical bookkeeping work includes:
- Capturing sales, purchases, receipts and payments.
- Reconciling bank feeds and payment processors.
- Maintaining customer and supplier ledgers.
- Preparing VAT records and supporting schedules.
- Processing payroll data or preparing payroll information.
- Flagging missing documents, unusual transactions and coding questions.
- Producing simple reports for the owner.
Good bookkeeping is not clerical in the dismissive sense. It is where errors are caught early. If a client mixes personal and business spending, forgets to invoice, pays suppliers twice, loses VAT evidence or records loan income as sales, the bookkeeper is often the first person to spot the pattern.
Accountancy scope
Accountancy usually sits above the ledger. It interprets, adjusts, reports and advises.
Typical small-practice accountancy work might include:
- Preparing sole trader accounts or limited company accounts.
- Supporting Self Assessment, Corporation Tax and VAT return preparation.
- Advising on business structure, drawings, dividends and salary planning.
- Reviewing management accounts with the owner.
- Supporting Companies House filings.
- Preparing forecasts and tax payment planning.
The risk level rises with interpretation. If you tell a client how to treat a complex transaction, whether expenditure is capital or revenue, or how to extract money from a company, you are no longer just keeping records tidy. Your engagement letter and professional competence need to match that service.
The commercial reality
Many small business owners do not want two advisers. They want one person who can keep them straight. That creates an opportunity for a combined bookkeeping and accountancy offer, but the package must be explicit.
A clear monthly package might say: "monthly bookkeeping, quarterly VAT return preparation, payroll for up to five employees, monthly management report, and one 30-minute review call." It should also say what is not included: company secretarial changes, tax investigations, loan applications, director personal tax, CIS, pension administration, or catch-up bookkeeping for old periods unless specifically agreed.
The more clearly you write the boundary, the easier it is to price the work fairly.
Professional Bodies, AML Supervision And Practice Status
Accountancy and bookkeeping are unusual because the public language is loose but the regulatory duties are not. A person can call themselves an accountant in many ordinary contexts, but that does not remove the need to follow supervision, professional body and restricted-work rules.
Anti-money laundering supervision is the first serious checkpoint.
GOV.UK tells accountancy service providers to check whether registration for money laundering supervision applies, either with HMRC or through a professional body supervisor. The relevant GOV.UK page is money laundering supervision registration for accountancy service providers. There is also accountancy sector guidance for money laundering supervision.
In practical terms, if you are offering bookkeeping, accounting, tax or payroll administration services to clients, treat AML supervision as an early launch checkpoint to confirm before trading. Do not wait until the first client asks. Client due diligence, risk assessment and ongoing monitoring need a place in your onboarding process from the start.
Professional bodies may be part of that route. Depending on your qualifications and membership, names you may encounter include AAT, ICB, IAB, ACCA, ICAEW, ICAS and CIMA. Each has its own rules for public practice, licences, supervision, ethics, CPD and insurance. A person who is employed in finance and capable at bookkeeping may still need a separate practice licence or supervision route before selling services to the public.
The key is not to collect logos. It is to know your status. Can you provide bookkeeping? Can you prepare accounts? Can you offer tax services? Can you use a protected designation? Do you need a practising certificate? Are you supervised for AML? What does your professional body say about professional indemnity insurance? Can your clients verify your status?
Write the answers down. They belong in your internal practice file, not just in your head.
HMRC Agent Services: Access Is Not Authority
HMRC access is another place where new practices can get muddled. Having an account is not the same as having authority for a client. Being asked by a client to "just log in for me" is not a suitable shortcut.
GOV.UK explains how to create an HMRC agent services account. It also explains how to get authorised to act as a tax agent on behalf of your clients. A new tax agent may need an agent services account, relevant agent codes, enrolments for services not accessed through that account, and client authorisation for each service.
Client authorisation can work differently depending on the tax service. GOV.UK refers to routes such as the digital handshake, online agent authorisation, paper forms, and authorisation through the client's business tax account. Build a checklist that records which services you are authorised for, when authority was requested, when it was accepted, and which services remain outside your access.
There is a simple rule for client credentials: do not use them. Read the GOV.UK guidance on how to get authorised to act as a tax agent and set up proper agent access instead. Your onboarding workflow should make that boundary normal from day one.
The HMRC standard for agents is also worth reading before launch. It gives guidance on minimum standards for tax agents and advisers, including conduct, client interaction and work with HMRC.
Clients often think authorisation is a formality. For your practice, it is a control point. No authority, no submission. Unclear authority, pause and resolve it. A missed deadline is painful; unauthorised access is worse.
Companies House Basics Worth Explaining To Clients
If you work with limited company clients, Companies House will become part of your everyday vocabulary. The trap is allowing directors to think that hiring an accountant transfers legal responsibility away from them.
Point company clients to the GOV.UK guidance on setting up a private limited company, which covers what directors stay responsible for even when they hire an accountant. GOV.UK also explains limited company duties around company and accounting records.
Your client education should cover the basics:
- What the company itself is responsible for, separately from its owners.
- Which accounting records directors need to keep (point them to the GOV.UK page).
- Which filings to expect each year, such as accounts and a confirmation statement, and who will prepare them.
- Which changes (directors, registered office, share structure or persons with significant control) to tell you about.
- Companies House information is public, so addresses and officer details need careful handling.
You can support the process, remind clients of deadlines and prepare information, but the engagement letter should be clear about who files what, who checks information before submission, and who remains responsible for telling you about changes.
This matters for tiny companies as much as for bigger ones. A one-director company with a few invoices can still miss a confirmation statement, forget to record a director loan, or assume dividends can be taken whenever there is cash in the bank. Your role is to reduce those avoidable surprises.
Build A Client Onboarding Workflow
Onboarding is where a small practice either becomes calm or becomes chaotic. A good onboarding workflow does not need to be elaborate. It needs to be repeatable.
Start with a triage call or questionnaire. You are looking for entity type, services needed, software used, number of bank accounts, VAT status, payroll headcount, CIS exposure, Companies House deadlines, HMRC authorisations needed, current record quality, previous adviser status, and immediate deadlines.
Then make a risk decision. A simple sole trader with current records and no urgent deadline is different from a company that has not filed accounts, has payroll arrears, mixed director loans and no bank reconciliations for eighteen months. Both may be good clients, but they are not the same job.
Your onboarding file will usually include:
- Client identity and business details.
- AML due diligence and risk assessment notes.
- Beneficial ownership details where relevant.
- Previous accountant professional clearance where appropriate.
- Software access and user permission record.
- HMRC authority status for each service.
- Companies House deadlines for limited company clients.
- Engagement letter and signed acceptance.
- Opening balances, prior returns and handover records.
- A first-month query log.
The engagement letter is the commercial anchor. It will usually name the client, the service scope, fee basis, payment terms, client responsibilities, your responsibilities, deadlines, data protection wording, confidentiality, AML checks, limitation wording, termination process, complaints route, and what happens when the client provides records late.
Do not treat this as paperwork for paperwork's sake. A well-written engagement letter prevents bad conversations later. It gives you a professional way to say "that is outside scope", "we need to reprice this", or "we cannot submit until you have reviewed the figures".
Data Protection, Confidentiality And ICO Basics
Accountants and bookkeepers handle a lot of personal data. Even a small practice may hold names, home addresses, email addresses, bank transactions, payroll records, National Insurance numbers, tax references, employee details and identity documents.
Check whether your practice needs to pay the data protection fee using the ICO data protection fee self-assessment. GOV.UK has a pay the data protection fee service, and the ICO has its own data protection fee guidance. The ICO's sector guidance for professional, scientific and technical activities explicitly includes accountancy, payroll, accountants and bookkeepers.
There's also a question worth asking your professional body or the ICO: in which parts of your work are you acting on a client's instructions, and in which are you deciding how data is used yourself? The answer affects privacy notices, retention, client requests and how you explain data use.
Your practical controls may include:
- A privacy notice clients can read before onboarding.
- A secure way to collect identity documents and payroll records.
- Multi-factor authentication on software and email where available.
- Limited staff access to client files.
- A retention policy for working papers and AML records.
- A data breach response process.
- Clear rules for using client information in marketing, testimonials or case studies.
Avoid broad data protection status claims. They sound neat but create claims you may struggle to evidence. Say what you actually do: follow ICO guidance, pay the data protection fee if required, use secure systems, limit access, keep retention rules and review data processes regularly.
Choose Software Without Turning It Into A Religion
Software choice matters. It affects speed, records, client experience and how much review work you can do before month-end becomes a scramble. But no software package fixes weak onboarding, poor scope control or missing evidence.
Start with your client mix. A sole trader with a handful of receipts needs something different from a VAT-registered company with payroll, directors' loans, payment processors and several bank accounts. A landlord, a tradesperson and an online shop will produce different records.
Look for practical fit:
- Bank feeds and reconciliation quality.
- VAT and payroll features where relevant.
- User permissions for staff and clients.
- Export options if a client leaves.
- Audit trail and attachment storage.
- Reporting that clients can understand.
- A sensible process for correcting errors.
- Integration with receipt capture, payroll or practice tools.
Do not use approval language for a product.
Spreadsheets still have a role. They can support pricing models, onboarding checklists, query logs, work-in-progress tracking, management reporting, simple internal reviews and client readiness checks.
This is where LaunchKit can help once your professional foundations are already clear. The accountant and bookkeeper hub groups templates by the way a small practice actually operates: documents, financial forms, pricing support and client-facing content. Treat templates as structure for your workflow, not as a substitute for professional judgement, AML supervision or software due diligence.
Price The Practice Around Risk, Volume And Behaviour
Pricing a bookkeeping or accountancy practice is harder than pricing a one-off trade job because the work changes with client behaviour. A client with 200 transactions, clean bank feeds and prompt queries may take less time than a client with 60 transactions, missing receipts and last-minute messages before every filing date.
Price drivers include:
- Monthly transaction volume.
- Number of bank accounts and payment platforms.
- VAT registration and return frequency.
- Payroll headcount and pay complexity.
- CIS, foreign currency or sector-specific records.
- Number of directors, shareholders or partners.
- Reporting cadence and advisory calls.
- Quality of opening records.
- Deadline pressure and catch-up work.
- How quickly the client answers queries.
Retainers can work well because many clients want predictability. The retainer should not be a vague promise to "do the accounts". It can tie fee to scope: monthly bookkeeping, VAT return preparation, payroll for a stated headcount, management report, year-end handover, tax return support, and a fixed review call if included.
Include fair movement rules. If transaction volume rises, payroll headcount changes, the client adds another bank account, or records arrive late every month, the retainer should be reviewed. That is not nickel-and-diming. It is how you keep the practice solvent and the service honest.
The Pricing Calculator Premium is an Excel workbook designed to help structure pricing inputs such as service type, time, retainer assumptions and add-on work. Use it as a modelling tool alongside your own experience and professional judgement. Do not let any calculator override the obvious: a messy, urgent, high-risk client needs more review time than a tidy client with predictable records.
For client education, it can help to link pricing to behaviour. "Your monthly fee assumes records are uploaded by the fifth working day" is much clearer than "please send things promptly". If records arrive after the agreed date, the deadline risk and rescheduling cost are real. Put that in the engagement letter.
The LaunchKit guide on keeping business expenses HMRC-ready in 15 minutes a week can also be useful as a client-facing habit piece. It is the kind of education that reduces avoidable query work without turning every email into a lecture.
Records, Working Papers And Review Habits
Your practice records are as important as the client's accounting records. If a client later asks why something was filed, why a transaction was treated a certain way, or what authority you had, your notes should help answer without drama.
HMRC guidance on business records if you're self-employed explains the need to keep records for tax. Limited companies have their own requirements, including accounting records. Your working papers sit alongside that: they are your evidence of work performed, queries raised, answers received and checks completed.
A practical engagement file will usually include:
- Signed engagement letter and variations.
- AML due diligence and risk notes.
- Professional clearance correspondence where relevant.
- HMRC authorisation evidence by service.
- Companies House filing calendar for company clients.
- Software access permissions.
- Privacy notice and data processing notes.
- Insurance and professional body status records for your own practice.
A practical job file will usually include:
- Trial balance or ledger exports.
- Bank reconciliation evidence.
- VAT workings and adjustments.
- Payroll summaries where relevant.
- Director loan review notes.
- Query log and client responses.
- Review notes before submission.
- Client approval evidence.
Review habits matter because bookkeeping errors rarely announce themselves politely. Build small checks into every month: unreconciled bank lines, negative balances, old debtors, duplicated supplier bills, unexplained suspense, VAT code oddities, payroll control differences and director loan movements. The habit is often more valuable than a heroic year-end rescue.
The Financial Forms bundle includes Income Tracker, Expense Tracker, Invoice, Client Payment Record and Profit & Loss among its exact listed forms. It does not include a client-communication template and does not replace review, evidence or professional judgement.
For clients who struggle to understand reports, point them towards plain-language explanations. LaunchKit's article on reading your monthly profit and loss is a useful companion when a client needs to understand margin, overhead and drawings rather than just stare at a report pack.
Quarterly Updates And Client Readiness
HMRC's digital records and quarterly updates for Income Tax change how many sole-trader and landlord clients work with an adviser. Check GOV.UK's guidance on whether and when quarterly updates apply for the current thresholds and dates rather than quoting them from memory. For a practice, it is a workflow change: digital records, software selection, client education, quarterly update habits and a clearer division of responsibility between client and adviser.
For a new practice, this does not mean every client needs the same package. It means client classification matters:
- In scope now or soon.
- Likely to come into scope later.
- Not currently in scope but still needing better records.
- Unsure because income sources or thresholds need checking.
Then build a conversation around readiness. Does the client have separate bank accounts? Are receipts captured quickly? Is property income mixed with trade income? Does the client understand quarterly updates? Is software already in place? Who will check figures before submission? What happens if the client misses the record deadline?
One client may need only quarterly review support. Another may need monthly bookkeeping, receipt capture, quarterly update preparation and a year-end review. A landlord with one property is different from a sole trader with several income streams and seasonal costs.
Use that honestly in your marketing. "We help you get records ready for quarterly reporting" is clearer than promising to make tax effortless.
Business Documents And The Client Experience
The administrative side of a practice can feel less exciting than tax work, but clients often judge professionalism through small moments: the proposal arrives clearly, the onboarding questions make sense, the engagement letter matches the conversation, and they know what to send next.
That is why document structure matters. You need repeatable versions of:
- Enquiry forms.
- Service proposals.
- Engagement letters.
- Privacy notices.
- Late records policy.
- Client responsibilities summary.
- Document request checklist.
- Fee review notice.
- Termination or disengagement wording.
The Business Documents collection is designed for this kind of small-practice admin. If you need deeper adaptation, Business Documents Premium includes editable DOCX files plus a separate fill-online browser bundle for business details and colours. Keep the distinction clear in your own buying decision: format matters when you plan to adapt wording for your practice.
Do not send template wording blindly. Accountancy and bookkeeping documents should reflect your professional body rules, services, insurance position, AML process, data handling and actual pricing model. A template gives you a starting structure; you still need to make it true.
The client experience should also include a short "how we work" page. Explain when records are due, how queries are handled, what happens before a return is submitted, which communication channel to use, and what counts as urgent. This one page can prevent dozens of small boundary problems.
If you are still choosing banking arrangements for your own practice, the LaunchKit article on choosing a UK business bank account is a useful operational companion. Keep client money, practice income and personal spending cleanly separated from the beginning.
Marketing A Practice Without Overpromising
Accountants and bookkeepers often under-market because they are rightly cautious. That caution is healthy, but it should not make your website vague.
Good marketing for this niche is specific:
- "Monthly bookkeeping for VAT-registered trades and consultants."
- "Cloud bookkeeping setup and clean-up for small limited companies."
- "Payroll, VAT records and management reports for owner-managed businesses."
Weak marketing says "we take the stress away" without naming the work. Strong marketing names the process and the boundary. It says who you help, what records you need, how the first month works and which services are not included.
Use it for general education and lead nurturing, not bespoke tax advice in public posts.
The same rule applies to AI-assisted copy. It can help draft first versions of posts or email prompts, but technical claims need human review. A small practice's reputation is built by being precise when everyone else is noisy.
Insurance And Risk Controls
Professional indemnity insurance is not glamorous, but it belongs near the beginning of the launch checklist. Several professional body routes require it for members in practice, and even where the exact requirement depends on your status, a client-facing bookkeeping or accountancy practice can treat professional indemnity cover as a serious risk control.
If you employ staff, check GOV.UK's employers' liability insurance guidance. Public liability may matter if clients visit your office or you visit theirs. Cyber cover may be worth considering because the practice handles financial and payroll data. If you work from home, check that your home insurance and mortgage or tenancy terms do not create problems.
Risk control is broader than insurance. It includes:
- Competence boundaries.
- Engagement letters.
- AML supervision and records.
- Secure software access.
- Two-person review where possible for risky work.
- Deadline tracking.
- Client approval before submission.
- Disengagement process for clients who repeatedly ignore controls.
The hardest control is saying no. A client who wants urgent accounts by Friday but cannot provide bank statements, payroll records or prior-year information may not be a bargain at any fee. A client who asks you to use their HMRC login has already shown you a boundary problem. A client who wants tax advice outside your competence needs a referral.
Small practices often grow because they are helpful. They survive because they are disciplined.
The First 90 Days Of A Small Practice
The first 90 days do not have to be a rush to collect as many clients as possible. A controlled build is usually easier to manage.
In weeks 1 and 2, settle the foundations. Confirm your professional body position, AML supervision route, insurance needs, service scope, excluded services and target client profile. Draft your engagement letter, privacy notice, onboarding checklist and pricing model. Decide what you will say when a client asks for something outside scope.
In weeks 3 and 4, build your operating system. Choose software based on client fit. Create a test client file and run it through the full journey: enquiry, due diligence, engagement letter, software access, HMRC authorisation, opening records, first month bookkeeping, query log, review and client report. You will find gaps before a paying client finds them.
In month 2, take a small number of pilot clients or controlled first clients. Avoid rescue work unless you have priced it and have enough time. Test your assumptions: how long onboarding takes, how many queries clients produce, how clean bank feeds are, how often payroll information arrives late, and whether your retainer wording is strong enough.
In month 3, review hard. Which clients were profitable? Which service lines created stress? Did your engagement letter protect the boundary? Did clients understand the monthly rhythm? Did your software stack create duplicate work? Are you attracting the right enquiries?
This is also when to start a simple education calendar. The goal is not to sound clever. It is to attract clients who value orderly records.
Common Mistakes To Avoid
The first mistake is taking client work before supervision and insurance are sorted. It feels productive in the moment, but it leaves the practice exposed before the foundations exist.
The second mistake is selling "everything" to win a client. Everything is not a service. It is an argument waiting to happen.
The third mistake is using client credentials because it is quicker. Build the correct HMRC authority process into onboarding and keep evidence.
The fourth mistake is letting software become the service. Clients pay for judgement, review, reminders, structure and accountability. Software is part of delivery.
The fifth mistake is weak pricing. If you price all clients by turnover or a rough monthly guess, you will undercharge complex clients and over-serve disorganised ones. Use volume, risk and behaviour.
The sixth mistake is avoiding hard client conversations. If records are late, say so. If scope has changed, reprice. If a client asks for regulated work, refer. The practice will feel more professional, not less.
FAQ
Do I need qualifications to start a bookkeeping business in the UK?
Don't treat professional status as optional. Check competence, AML supervision, professional body rules if you are a member, insurance expectations and whether any service you plan to offer is restricted or separately authorised.
Do bookkeepers need AML supervision?
Many accountancy service providers, including bookkeeping and payroll administration providers, need anti-money laundering supervision through HMRC or a professional body supervisor. Check the GOV.UK accountancy service provider guidance before taking clients.
Can I act as an HMRC agent for clients?
Yes, if you have the right HMRC agent setup and the client has authorised you for the relevant service. An agent services account is not the same as authority for every client or every tax service. Keep service-by-service evidence.
What should an engagement letter include?
It will usually include the client name, service scope, fees, payment terms, responsibilities, deadlines, data protection wording, AML checks, confidentiality, limitation wording, complaint route, termination process and late records policy. It should also make excluded services clear.
Do accountants and bookkeepers need to pay the ICO fee?
Check with the ICO. Accountants and bookkeepers handle a lot of client personal data, so use the ICO fee self-assessment and its sector guidance for accountancy and payroll.
How should I price monthly bookkeeping retainers?
Use scope, transaction volume, VAT status, payroll headcount, bank accounts, reporting cadence, record quality, deadline pressure and client behaviour. A retainer should include clear limits and a review trigger when the work changes.
When clients come into scope for quarterly updates, review the retainer too: classifying clients, setting record deadlines, choosing software, reviewing quarterly update habits and explaining responsibilities clearly all take time.
Can I use spreadsheets in a bookkeeping practice?
Yes, spreadsheets can support pricing, onboarding, review logs, management reporting and internal controls.
By the LaunchKit team
Sources Checked And How To Use This Guide
Last reviewed: May 2026.
Sources checked while preparing this guide:
- money laundering supervision registration for accountancy service providers
- accountancy sector guidance for money laundering supervision
- create an HMRC agent services account
- how to get authorised to act as a tax agent on behalf of your clients
- HMRC standard for agents
LaunchKit guides and templates are designed to help with business admin, planning, pricing, records and customer-facing paperwork. They are not legal, tax, medical, safeguarding, planning or regulatory advice. For regulated work, check the current official guidance and take professional advice where needed.
Author
By the LaunchKit team.
Next useful links
Build out your accountant / bookkeeper setup
Accountant / Bookkeeper business templates
See the LaunchKit hub for accountant / bookkeeper.
Professional Services templates
Compare related professional services business resources.
Accountant Bookkeeper Pricing Calculator — Premium
An Excel workbook (.xlsx) for UK accountancy and bookkeeping practices. It prices each engagement as hours × your hourly rate, plus materials with a markup, plus a…
Accountant Bookkeeper Financial Forms Bundle — Premium
11 distinct financial record templates for accountancy and bookkeeping businesses, each supplied as a fillable PDF and an editable DOCX file.
Keeping your business expenses HMRC-ready in 15 minutes a week
The single biggest source of January misery for UK sole traders is reconstructing twelve months of business expenses from a drawer of receipts, a fragmented bank statement, and memory…
Reading your monthly profit and loss: the three numbers most sole traders ignore
Most UK sole traders judge how their business is doing by looking at their bank balance. End of the month, balance is up, things are good. End of the month, balance is down, time to worry.
LaunchKit
Templates and documents built for accountant / bookkeeper.
Get your accountant / bookkeeper kit →Related LaunchKit tools
Templates mentioned in this guide
Accountant Bookkeeper Pricing Calculator — Premium
What you get
- Work out a price from your hours, hourly rate, materials and a fixed fee
- Includes Service Pricing, Quote Builder and Quote Output, plus 5 more
- Best used in Microsoft Excel · Instant access
Accountant Bookkeeper Financial Forms Bundle — Premium
What you get
- 11 distinct financial record templates — fillable PDF, editable DOCX, and one fill-online HTML bundle
- Includes Cash Flow Forecast, Client Payment Record and CPD Training, plus 8 more
- Fillable PDF + DOCX + fill-online HTML · Two secure downloads
Accountant Bookkeeper Business Documents — Premium
What you get
- 17 business-record templates — fillable PDF, editable DOCX, and one fill-online HTML bundle
- Includes Client Registration Onboarding, AML KYC Checklist and Client Id Verification Record, plus 14 more
- Fillable PDF + DOCX + fill-online HTML · Two secure downloads
More tips for accountant / bookkeeper
Free advice, templates and product updates. No spam.